Sell My House Fast in Memphis, TN
Need to sell your house fast in Memphis? We’re local cash buyers who can make a written offer within 24 hours and close in as little as 7 days—no repairs, no showings, no agent commissions, and no waiting on a bank.
Get Your Free Cash Offer
No obligation · takes 30 seconds
How Fast Can You Sell a House in Memphis, TN?
When you sell to a cash buyer, the slow parts of a traditional sale simply disappear—no listing photos, no open houses, no mortgage underwriting, and no appraisal. Here’s what the timeline usually looks like with us.
Same day
You call or send the address. We ask a few questions about the house and your timeline—no inspection required to get started.
Within 24 hours
You get one clear, written cash offer with no obligation. We walk you through exactly how we reached the number.
Days 2–5
If you accept, a licensed Memphis title company opens title and confirms there are no liens or claims to clear.
Day 7+
We close on the date you choose. You walk away with a check or wire—often in about a week once title is clear.
Why a Fast Sale Often Beats Waiting for the Market
A traditional Memphis listing can look great on paper, but the calendar costs real money. Every month a house sits, you’re still paying the mortgage, property taxes, insurance, utilities, and upkeep—and that’s before a single repair request from an inspection. On top of that, roughly one in six financed deals nationwide falls apart late in the process when a buyer’s loan is denied, sending you back to square one after weeks of waiting.
People who need to sell my house fast in Memphis are usually watching a date they cannot move: a job in another city, a Shelby County foreclosure sale, or an estate that is still paying the light bill. A financed buyer often needs another 30 to 45 days after the contract just for underwriting, and that clock starts over if the loan is denied.
A cash offer trades a retail-level price for certainty: a firm number, a firm date, and no financing to fall through. If keeping the house is the better outcome, a HUD-approved housing counselor can review options at no cost. If selling is the right move, we’ll say so plainly—and we’ll put the timeline in writing.
When Memphis Homeowners Need to Sell Fast
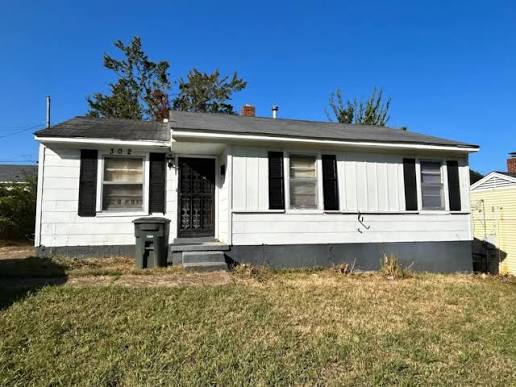
We buy houses fast in every Memphis ZIP code and across Shelby County. Most of our calls come from one of these situations:
Facing foreclosure
A sale date is coming and you need to pay off the loan before the auction. See facing foreclosure.
Job relocation
You have to be in a new city on a deadline and can’t carry two housing payments. See relocating.
Inherited a house
You’re managing a parent’s Memphis home from out of town and want it off your plate. See inherited property.
Divorce
Both parties need a clean, fast split of the equity without a drawn-out listing. See divorce.
Tired of being a landlord
A problem rental is costing more than it earns and you want out now. See tired landlord.
Vacant or problem property
An empty house is racking up bills, code letters, or vandalism risk. See vacant or abandoned.
What Can Slow a Fast Sale Down—and How We Handle It
A true 7-day close depends on clean title. A few things can add time, and we’d rather name them up front than surprise you: an open probate case (the estate has to be opened in Shelby County before anyone can sign), unpaid tax or judgment liens that must be paid from the proceeds, or a missing heir or co-owner who also has to sign. The Tennessee courts site explains how probate generally works; the estate’s attorney can tell you what this house still needs.
None of these stop a sale—they just change the date. We work with a local title company that clears these issues every week, and we can set the closing to line up with the court or the payoff. Tennessee records the deed with the Shelby County Register of Deeds and charges a transfer tax of 37 cents per $100 of value, which we typically cover along with standard closing costs. Owners who sell my house fast in Memphis still get that recorded deed; the difference is you are not waiting on a lender to schedule the signing.
Selling Fast in Memphis, TN: FAQ
How fast can you really close?
Many Memphis purchases close in about 7–14 days once title is clear. If you need more time to move or to wait on an estate, we set a later date that works for you—you’re always in control of the calendar.
Do I need to make any repairs first?
No. We buy as-is. Leave what you don’t want, skip the cleaning, and take only what matters to you. The repairs are our problem after closing, not yours.
Is there any cost or obligation to get an offer?
None. The offer is free, there’s no obligation to accept, and there are no agent commissions or hidden fees if you do.
Can you still buy if I’m behind on payments or in foreclosure?
Yes. As long as there’s a sale date we can work backward from, we can often close in time to pay off the loan and protect any remaining equity. A HUD-approved counselor can also review options if you’d rather keep the home.